Megan Conceição looks at how the “K-Shaped” economy is impacting beverages
| The big idea:
· Regardless of income level, consumers are becoming more intentional with their spending. · Brands offering either great value, or a premium experience are thriving, while the middle of the market is coming under increasing pressure. · Success is more about having a clear and defensible role in consumers’ lives. |
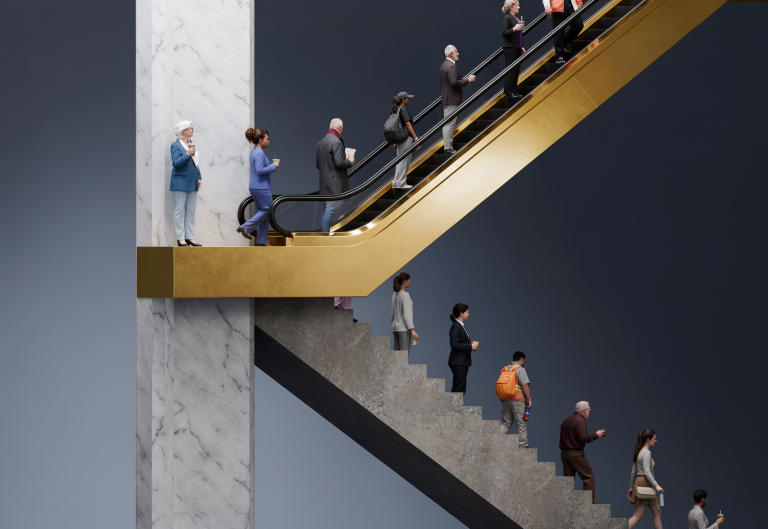
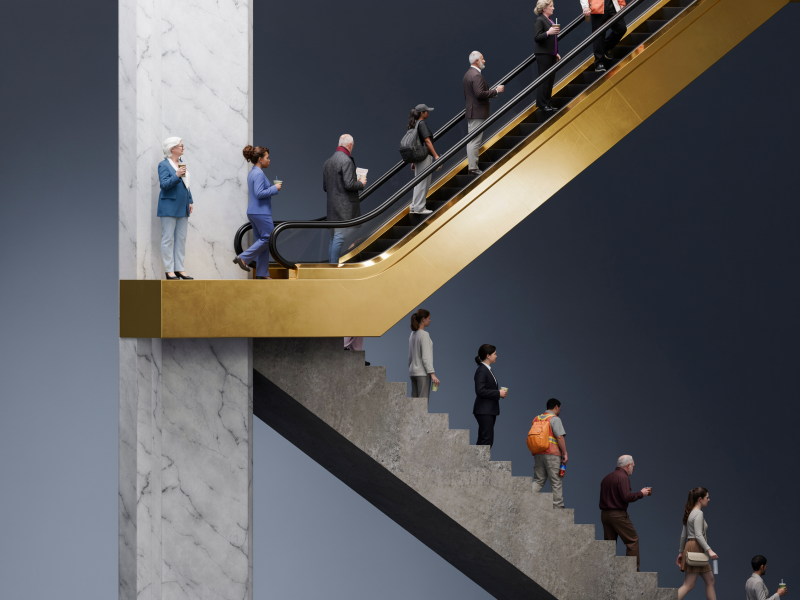
The concept of a K-shaped economy has gained traction in recent years. The model describes a landscape in which spending patterns diverge sharply across income groups, bifurcating like the letter K.
The model posits that the uneven post pandemic recovery – where premium priced apps like DoorDash thrive at the same time that fast-food restaurants rely on value meals – is due to a widening gap in consumer spending power. High income consumers, buoyed by stock market gains and rising asset values, continuing to spend freely, while lower income households, squeezed by inflation and rising living costs, are becoming increasingly selective about where and how they spend. Data from the US Federal Reserve appears to support this view, with the wealthiest 1% of Americans accounting for a record 32% of total wealth in the third quarter of 2025.
Selective spending
While the consumer landscape has undoubtedly become more polarized over the past decade, we believe this divergence cannot be explained solely
by differences in financial circumstances. Equally important has been a broader shift in consumer mindset. Regardless of income level, consumers are becoming more intentional with their spending – saving where they can, so they can selectively splurge where they choose.
This shift is reshaping the food and beverage industry. From category dynamics and pricing strategies to portfolio architecture, brands are being forced to adapt to a more polarized marketplace.
Contradictory consumers
One of the defining dynamics of this decade has been the emergence of seemingly contradictory spending behaviors. On one hand, discretionary purchases such as Labubus and $20 celebrity smoothies have skyrocketed in popularity, while some mainstream brands have struggled to maintain momentum.
On the other, private-label brands – historically positioned as undifferentiated budget alternatives – have evolved into formidable competitors. Retailers such as Marks & Spencer in the UK and Trader Joe’s in the US have built private-label portfolios with cult-like followings that rival many household-name brands.
While this environment can make it difficult to predict which categories and brands will succeed, the contradiction reveals a broader reality: consumers are neither uniformly trading up nor trading down. Instead, they are becoming increasingly selective, directing their spending towards products and brands that deliver either exceptional value or a compelling reason to pay more.
Importantly, this shift is largely income agnostic. Recent research by McKinsey found that high-income consumers are more likely to adopt selective cost-optimization behaviors like DIYing services, and use budgeting tools, enforcing the fact that selective spending is no longer just a response to financial pressures.
Face value
In this world, the power of being a value brand is clear: cost-savings. For lower income consumers, they provide much needed financial relief; for higher-income consumers, they represent an opportunity to economize in less important areas, freeing up budget for purchases that matter more.
In foodservice, this strategy has helped operators such as McDonald’s and Taco Bell drive traffic through compelling value platforms. Taco Bell’s Luxe Cravings menu, for example, has proven particularly successful, with one third of transactions now including a value-menu item. In retail, private-label brands have similarly benefited from consumers’ desire to spend more intelligently without feeling as though they are compromising on quality
Accessible status
At the other end of the spectrum, premium brands are thriving for a different reason. In an environment where food and beverages increasingly serve as extensions of personal identity, consumers are willing to pay more for products that help them express who they are and who they aspire to be. This is particularly true among Gen Z and Gen Alpha consumers, for whom consumption is often highly visible and socially mediated.
As rising costs have pushed traditional luxury further out of reach, food and beverages have emerged as more accessible status symbols. Whether it’s a buzzy functional brand like David’s (most recently endorsed by Bella Hadid), Happy Grocer, the viral, green-juice touting health store or Ghia, the trendy non-alcoholic drinks brand, these purchases offer consumers an affordable indulgence.
More importantly, they allow consumers to communicate identity, signal values, and align themselves with an aspirational version of themselves.
Mid-market malaise
The middle of the market, however, is coming under increasing pressure. Across both retail and foodservice, mainstream brands positioned between value and premium are finding it harder to justify their place in consumers’ repertoires, facing competition from both ends of the spectrum.
In foodservice, casual dining chains have been among the biggest casualties of this shift. Data from Technomic shows that the segment has lost more than 200 locations in the last two years, as chains like Applebee’s, and Red Lobster grapple with the challenge of being neither the cheapest nor the most distinctive.
At the same time, leading operators are embracing this deepening bifurcation rather than trying to compete in the middle. McDonald’s, for example, for who value meals have driven success, is also experimenting with premium activations. Earlier this year, the chain partnered with Paramount Caviar to launch a limited edition caviar kit, pairing their chicken nuggets with Baerii sturgeon caviar. While the kit was a Valentine’s Day marketing effort rather than a commercial offering, it reflected a growing recognition that consumers are increasingly drawn to both ends of the value spectrum.
Winning with Purpose
Ultimately, success in today’s market is less about being the cheapest option and more about having a clear and defensible role in consumers’ lives. As consumers become increasingly deliberate with their spending, brands that deliver either outstanding value or meaningful differentiation are best positioned to win. Those caught in the middle risk becoming increasingly irrelevant.
Megan Conceição, Customer Insights Manager
Finlays Solutions